
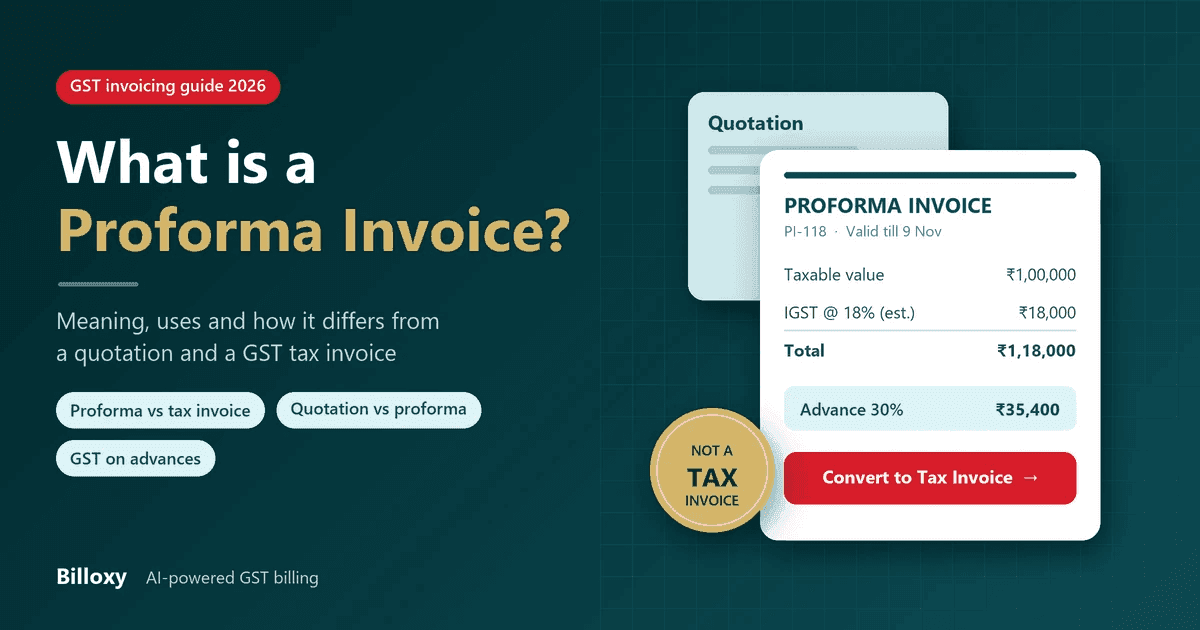
A proforma invoice is a preliminary bill a seller sends before the sale is final. It lists the goods or services, prices, expected GST, delivery and payment terms, so the buyer knows what they will be billed. It is not a GST tax invoice: that is issued when the supply is made.
Updated 23 October 2026. This guide is for Indian MSMEs that send quotes and proformas before billing: wholesalers and distributors, manufacturers, B2B traders, contractors and service firms. It compares the proforma with a quotation, a tax invoice and a receipt voucher, and explains the GST points that matter. It is not tax advice. For your own case, check with your chartered accountant.
Proforma invoice meaning in simple words
"Pro forma" means "as a matter of form". A proforma invoice looks like an invoice, but it is a promise of what the invoice will say, sent while the deal can still change.
Typical moments when an Indian business sends one:
- A buyer has accepted your quote and asks for a proforma to get internal approval or arrange funds.
- You want an advance before you buy material, start production or dispatch the goods.
- A customer wants the final GST amount, freight and delivery date in writing before placing the order.
- An overseas buyer or their bank asks for a proforma before arranging payment for an export order.
If the buyer changes the quantity, price or delivery terms, you send a revised proforma. Nothing is booked as a sale yet.
What should a proforma invoice include?
GST law does not prescribe a proforma invoice format, so there is no official list of fields. In practice, a clear proforma carries the same details the buyer will later see on the tax invoice, so the two documents match:
| Field | Why it matters |
|---|---|
| The words "Proforma Invoice" at the top | Stops the buyer from treating it as a tax invoice |
| Proforma number and date | Lets you track revisions (PI-001, PI-001-R1) |
| Validity date | Prices and stock are held only until this date |
| Your business name, address and GSTIN | Same as on your tax invoices |
| Buyer name, address and GSTIN (if registered) | Lets the buyer check the place of supply and tax type |
| Item description, HSN or SAC code, quantity and unit | Avoids disputes when the goods arrive |
| Rate, discount and taxable value per line | The basis of the final bill |
| Expected GST rate and amount (CGST + SGST or IGST) | Shows the full landed cost to the buyer |
| Freight, packing and other charges | No surprises on the final invoice |
| Payment terms and advance asked | For example, 30% advance, balance before dispatch |
| Delivery terms and expected dispatch date | Sets expectations for both sides |
| Bank details and a signature | So the buyer can pay the advance |
For the fields that are mandatory on the final bill, see mandatory fields in a GST invoice.
Proforma invoice vs tax invoice: what is the difference?
The short answer: a proforma invoice is a pre-sale estimate, while a tax invoice is the legal record of the sale under GST. Section 31 of the CGST Act requires a registered person to issue a tax invoice for a taxable supply, and Rule 46 sets out what it must contain.
| Point | Proforma invoice | Tax invoice |
|---|---|---|
| When it is issued | Before the sale, while terms can change | At or before the supply of goods; within the prescribed time for services |
| Purpose | Quote the final terms, ask for confirmation or an advance | Record the sale and charge GST |
| Required by GST law? | No | Yes, under Section 31 of the CGST Act |
| Can it change? | Yes, by a revised proforma | Changes go through a credit note or debit note |
| Reported in GSTR-1 and GSTR-3B? | No | Yes, in the return for its tax period |
| Buyer can claim input tax credit on it? | No. Rule 36 lists the documents for ITC, and a proforma is not one of them | Yes, if the other ITC conditions are met |
| Entered in your sales book? | No | Yes |
| Numbering | Your own proforma series | A consecutive serial number, unique for the financial year (Rule 46) |
Read more about the final bill in what is a GST invoice? and when should a GST invoice be issued?
Quotation vs proforma invoice
Both come before the sale, but they sit at different stages:
| Point | Quotation | Proforma invoice |
|---|---|---|
| Stage | Early. The buyer is still comparing prices | Later. The buyer intends to buy |
| What it says | "This is our price if you order" | "This is what your invoice will be when we supply" |
| Detail | Often item rates only | Full quantities, taxes, charges, payment and delivery terms |
| Typical next step | Negotiation or a purchase order | An advance payment, then dispatch and the tax invoice |
Many small businesses skip one of the two. That is fine, as long as the buyer knows which document is the binding final bill: the tax invoice.
Proforma, receipt voucher and tax invoice: the order of documents
A common B2B sale with an advance moves through these documents:
- Quotation. You share your price.
- Proforma invoice. The buyer confirms the order, and you send the final terms with the advance you need.
- Receipt voucher. When the advance arrives, Section 31(3)(d) of the CGST Act requires a registered person to issue a receipt voucher (or another document) as evidence of the payment. Rule 50 lists its contents: your GSTIN, a serial number, the date, the buyer's details, the description, the amount of the advance, the tax rate and the tax amount.
- Tax invoice. You issue it when you supply, and it is the document that goes into your GST returns.
- Refund voucher (only if the deal is cancelled). If you took an advance and issued a receipt voucher but no supply follows, Section 31(3)(e) allows you to issue a refund voucher against that payment.
Where goods move without a sale (for example to a job worker), the document is a delivery challan under Rule 55, not a proforma.
Is GST payable when you issue a proforma invoice?
No. Issuing a proforma does not create GST liability, because no supply has taken place and it is not a tax invoice. What can create liability is the advance the buyer pays against it:
- Goods. Under Notification No. 66/2017-Central Tax, registered suppliers of goods, other than composition taxpayers, pay GST when the tax invoice is issued, not when the advance is received.
- Services. GST is payable on an advance for services when you receive it, because the time of supply is the earlier of the invoice date and the payment date.
- Rate unclear at the time of the advance. Under the proviso to Rule 50, if the tax rate cannot be determined, tax is paid at 18%. If the nature of supply cannot be determined, it is treated as an inter-state supply.
The full rules, with examples, are in what is time of supply under GST?
A worked example
A Surat wholesaler (registered in Gujarat) gets an order from a Pune retailer (registered in Maharashtra) for goods worth ₹1,00,000. For this example, assume the goods are taxed at 18%. Always check the current rate for your HSN code.
- Proforma invoice PI-118, 2 November. Taxable value ₹1,00,000. IGST at 18% = ₹18,000, because this is an inter-state supply. Total ₹1,18,000. Terms: 30% advance, balance before dispatch. Valid till 9 November.
- Advance of ₹35,400 received on 4 November. The wholesaler issues a receipt voucher. As a regular supplier of goods, they do not pay GST on this advance (Notification No. 66/2017-Central Tax).
- Dispatch on 12 November. The wholesaler issues tax invoice INV-2026-27/0542 for ₹1,18,000, showing the ₹35,400 already received. This invoice, not the proforma, goes into November's GSTR-1, and the retailer claims ITC on it.
If the retailer had cancelled before dispatch, the wholesaler would issue a refund voucher for the ₹35,400.
Common proforma invoice mistakes
- Not labelling the document "Proforma Invoice". The buyer's accountant may book it as a purchase and claim credit on it.
- Using the tax invoice number series for proformas. Tax invoice numbers must run consecutively for the financial year. Keep a separate proforma series.
- Reporting proformas in GSTR-1. A proforma is not reported. Your returns carry the tax invoices, credit and debit notes, and taxable advances.
- Forgetting the receipt voucher when an advance arrives. This applies especially to services, where the advance is taxable.
- Letting the proforma and the tax invoice drift apart. Re-typing items and prices on the final bill is where quantity, rate and GST errors creep in. If the buyer negotiated a change, send a revised proforma first.
- No validity date. Old prices get held against you when material costs rise.
How Billoxy handles proforma invoices
Billoxy's Quotation & Proforma module keeps the documents before the bill in one place, under Sales → Proforma Invoices:
- Create a quotation or proforma for a customer with the item's sales price, tax, discounts and totals, using the same logic as a sales order.
- Save it as a draft, preview it in a PDF template, then download, print or share it by WhatsApp or email.
- Open the related sales order when the proforma came from one.
- Convert the proforma to a sales invoice when the customer confirms, so the customer, items, prices, tax and totals carry over to the final bill instead of being typed again.
- Set reminders 3 days before, on, and 1 day after the due date through WhatsApp, SMS and email.
You can try it on your own business data with the 10-day free trial. If you need only one GST invoice right now, the free GST invoice generator builds one without signing up.
Questions businesses ask about proforma invoices
Is a proforma invoice legally valid?
It is a valid commercial document between buyer and seller, and the buyer can rely on it to approve an order or pay an advance. It is not a tax invoice under GST, so it cannot be used to charge GST, report a sale or claim input tax credit.
Can I claim input tax credit on a proforma invoice?
No. Rule 36 of the CGST Rules allows ITC only on the documents it lists: a tax invoice, a debit note, a bill of entry and certain other documents. A proforma invoice is not one of them. Wait for the supplier's tax invoice.
Should a proforma invoice show GST?
It usually should. Showing the expected GST rate and amount tells the buyer the full cost. The tax is actually charged on the tax invoice.
Does a proforma invoice need a GSTIN?
There is no prescribed format, but showing your GSTIN and the buyer's GSTIN helps the buyer check the place of supply and whether CGST + SGST or IGST will apply.
Is a proforma invoice the same as a quotation?
Not quite. A quotation is an early price offer. A proforma invoice comes after the buyer intends to buy and shows the full terms of the final invoice, often with an advance request.
Is a proforma invoice reported in GSTR-1?
No. GSTR-1 reports tax invoices, credit and debit notes and advances received. The proforma itself is not reported.
What happens if the buyer cancels after paying an advance?
If you issued a receipt voucher for the advance and no supply is made, you may issue a refund voucher against that payment, as Section 31(3)(e) of the CGST Act allows.
Related Billoxy guides
- What is a GST invoice?
- Mandatory fields in a GST invoice
- GST invoice vs bill of supply
- What is time of supply under GST?
- How to manage overdue invoices
Official sources
- Section 31, CGST Act 2017 — Tax invoice, receipt voucher and refund voucher — CBIC
- Rule 46, CGST Rules — Tax invoice — CBIC
- Rule 50, CGST Rules — Receipt voucher — CBIC
- Rule 55, CGST Rules — Delivery challan — CBIC
- Rule 36, CGST Rules — Documents for claiming input tax credit — CBIC
- Time of Supply in GST — GST flyer — GST Council